What is a green car loan, and are electric car loans cheaper?
A green car loan is a car loan where the lender offers special pricing because the vehicle is electric or low-emission. Not every lender has one, and each sets its own rules about which cars qualify.
That’s where we earn our keep. We know which lenders on our panel price electric car loans more keenly and which models make the cut, so you don’t have to ring around.
You’d be in good company. Battery-electric vehicles made up about 8.3% of new-vehicle sales in 2025, up from 7.4% the year before – and those cars will steadily flow into the used market too.
How does the EV FBT exemption work?
The Electric Car Discount exempts eligible zero- and low-emission cars from fringe benefits tax when they’re provided through an employer – most often via a novated lease and salary packaging. The car must be valued under the fuel-efficient luxury car tax threshold.
Plug-in hybrids stopped qualifying from 1 April 2025, unless already under an arrangement before then. On 5 May 2026 the Government announced phased changes; legislation details are still pending, but this is the timeline it outlined:
| Period | What’s proposed |
|---|---|
| Until 31 March 2027 | No change – eligible EVs under the fuel-efficient LCT threshold keep the full exemption |
| 1 April 2027 – 31 March 2029 | EVs valued at $75,000 or less keep the full exemption; those above $75,000 (but under the threshold) get a 25% FBT discount |
| From 1 April 2029 | All eligible EVs get a 25% discount instead of a full exemption |
EV loan vs novated lease: which suits you?
It comes down to how you earn, how long you’ll stay with your employer and if you’d like the car in your name from day one. A novated lease can deliver tax savings on an eligible EV; an EV loan keeps things simple and portable.
| EV car loan | Novated lease | Paying cash | |
|---|---|---|---|
| Ownership | Yours from day one; the car secures the loan | Held by the lease provider until the residual is paid | Yours outright |
| Tax angle | Generally none for personal use | FBT exemption may apply to eligible EVs | None |
| Tied to your job? | No | Yes – runs through your employer’s payroll | No |
| End of term | Pay any balloon you chose | A residual payment falls due | Nothing owing |
| Suits | Self-employed people, contractors, simplicity seekers | Employees offered salary packaging | Buyers with savings they won’t miss |
Our guide to novated lease vs car loan digs deeper into the pros and cons.
What EV can I get under the LCT threshold?
For 2026–27, the luxury car tax threshold for fuel-efficient vehicles is $91,661, up from $91,387 in 2025–26. Battery-electric cars fall into the fuel-efficient category, so that’s the number to keep in mind.
- Under the threshold – no luxury car tax, and the car may be eligible for the FBT exemption on a novated lease.
- Over it – LCT applies to the value above the threshold, and the FBT exemption is off the table.
- Close to the line? Options and accessories add to the car’s value, so check the final drive-away figure.
Can I finance a home charger with my EV?
Often, yes. Some lenders let you include a wall charger and its installation in your electric car loan, particularly when it’s bought as part of the package. Otherwise, a small separate loan can cover it.
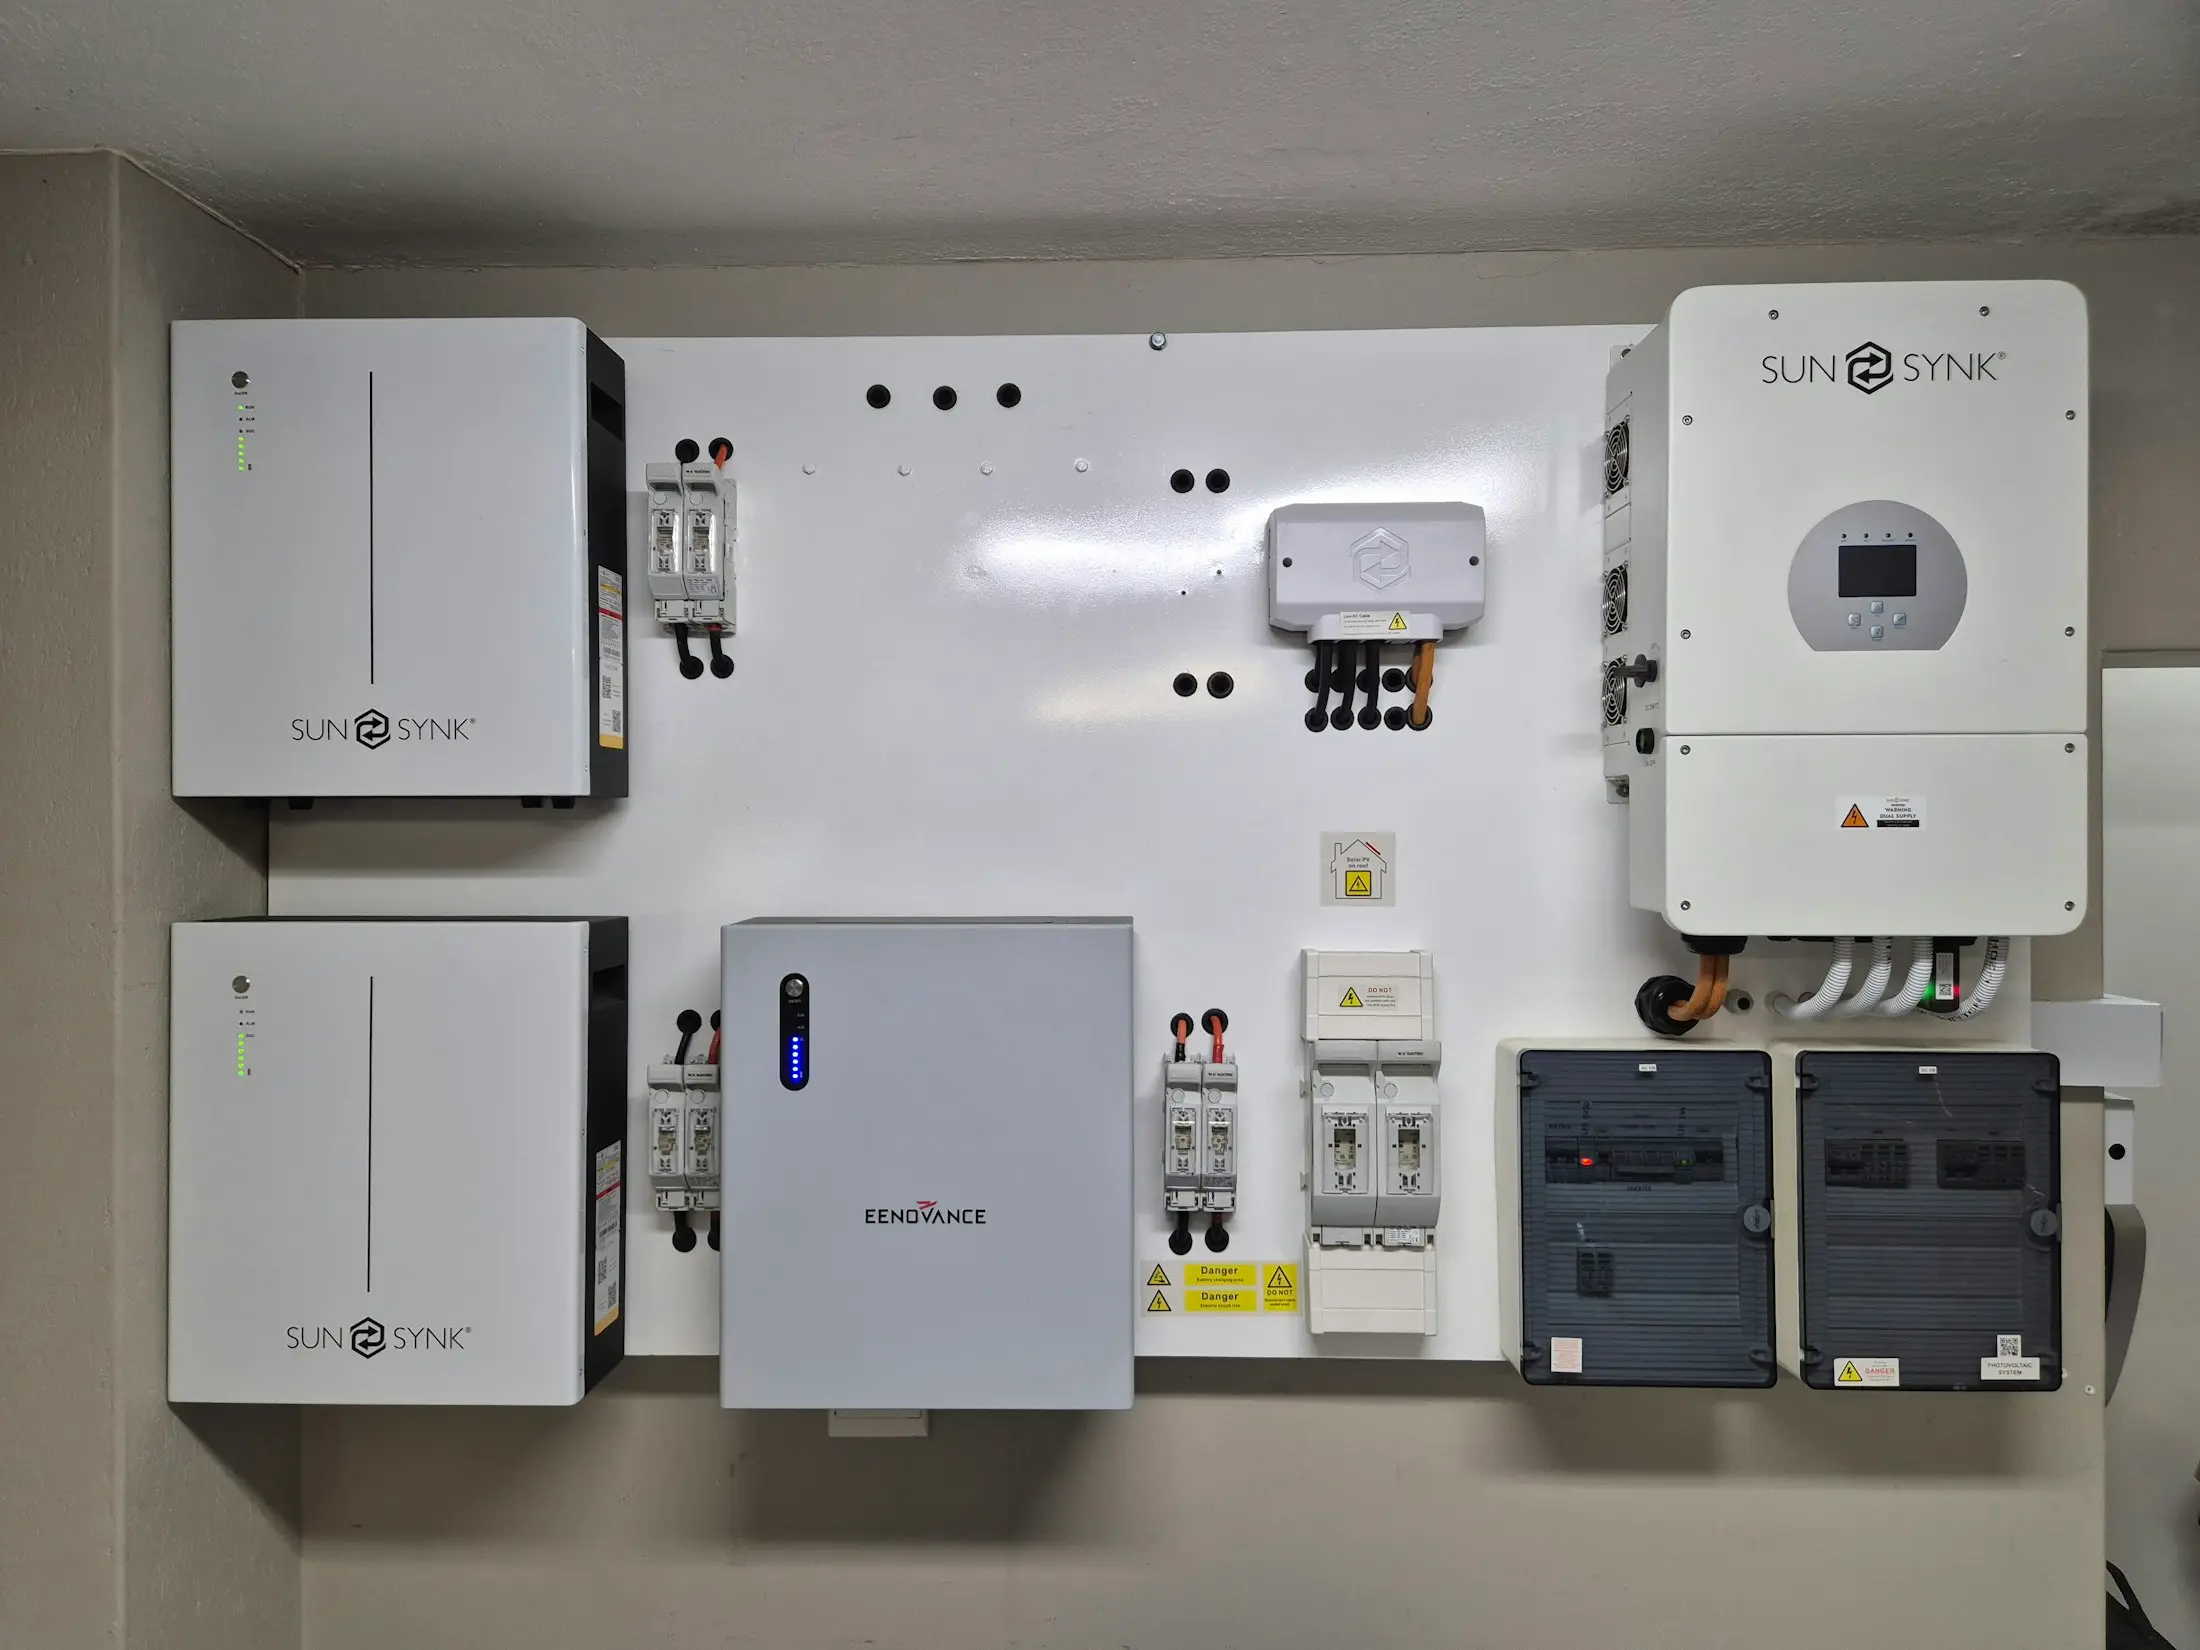
The dream setup is charging overnight off your own solar and battery. The federal Cheaper Home Batteries Program takes roughly 30% off the upfront cost of an eligible battery installed with rooftop solar, and home battery loans can help with the rest.
Can I finance a used EV?
Yes – a used EV can be financed like any used car, within the lender’s age and condition limits. What changes is the homework before you buy:
- Battery health report – ask for a state-of-health reading; it’s the EV version of a mechanic’s check.
- Battery warranty – see how many years and kilometres are left.
- Charging gear – confirm the portable cable and any adaptors come with the car.
- PPSR check – the same search for money owing and written-off history you’d run on any used car.
What you’ll need
- A current driver licence
- Recent payslips, or tax returns if you’re self-employed
- The EV’s quote or invoice, including any charger
- Salary packaging details from your employer, for a novated lease
- A summary of your living expenses and existing debts
- Battery health report and PPSR result for a used EV
Who it usually suits
- 18 or over with stable, verifiable income
- Australian citizenship or permanent residency (some lenders consider visa holders)
- For a novated lease: an employer that offers salary packaging
- Repayments that sit comfortably within your budget
- Credit history with a few marks is assessed case by case