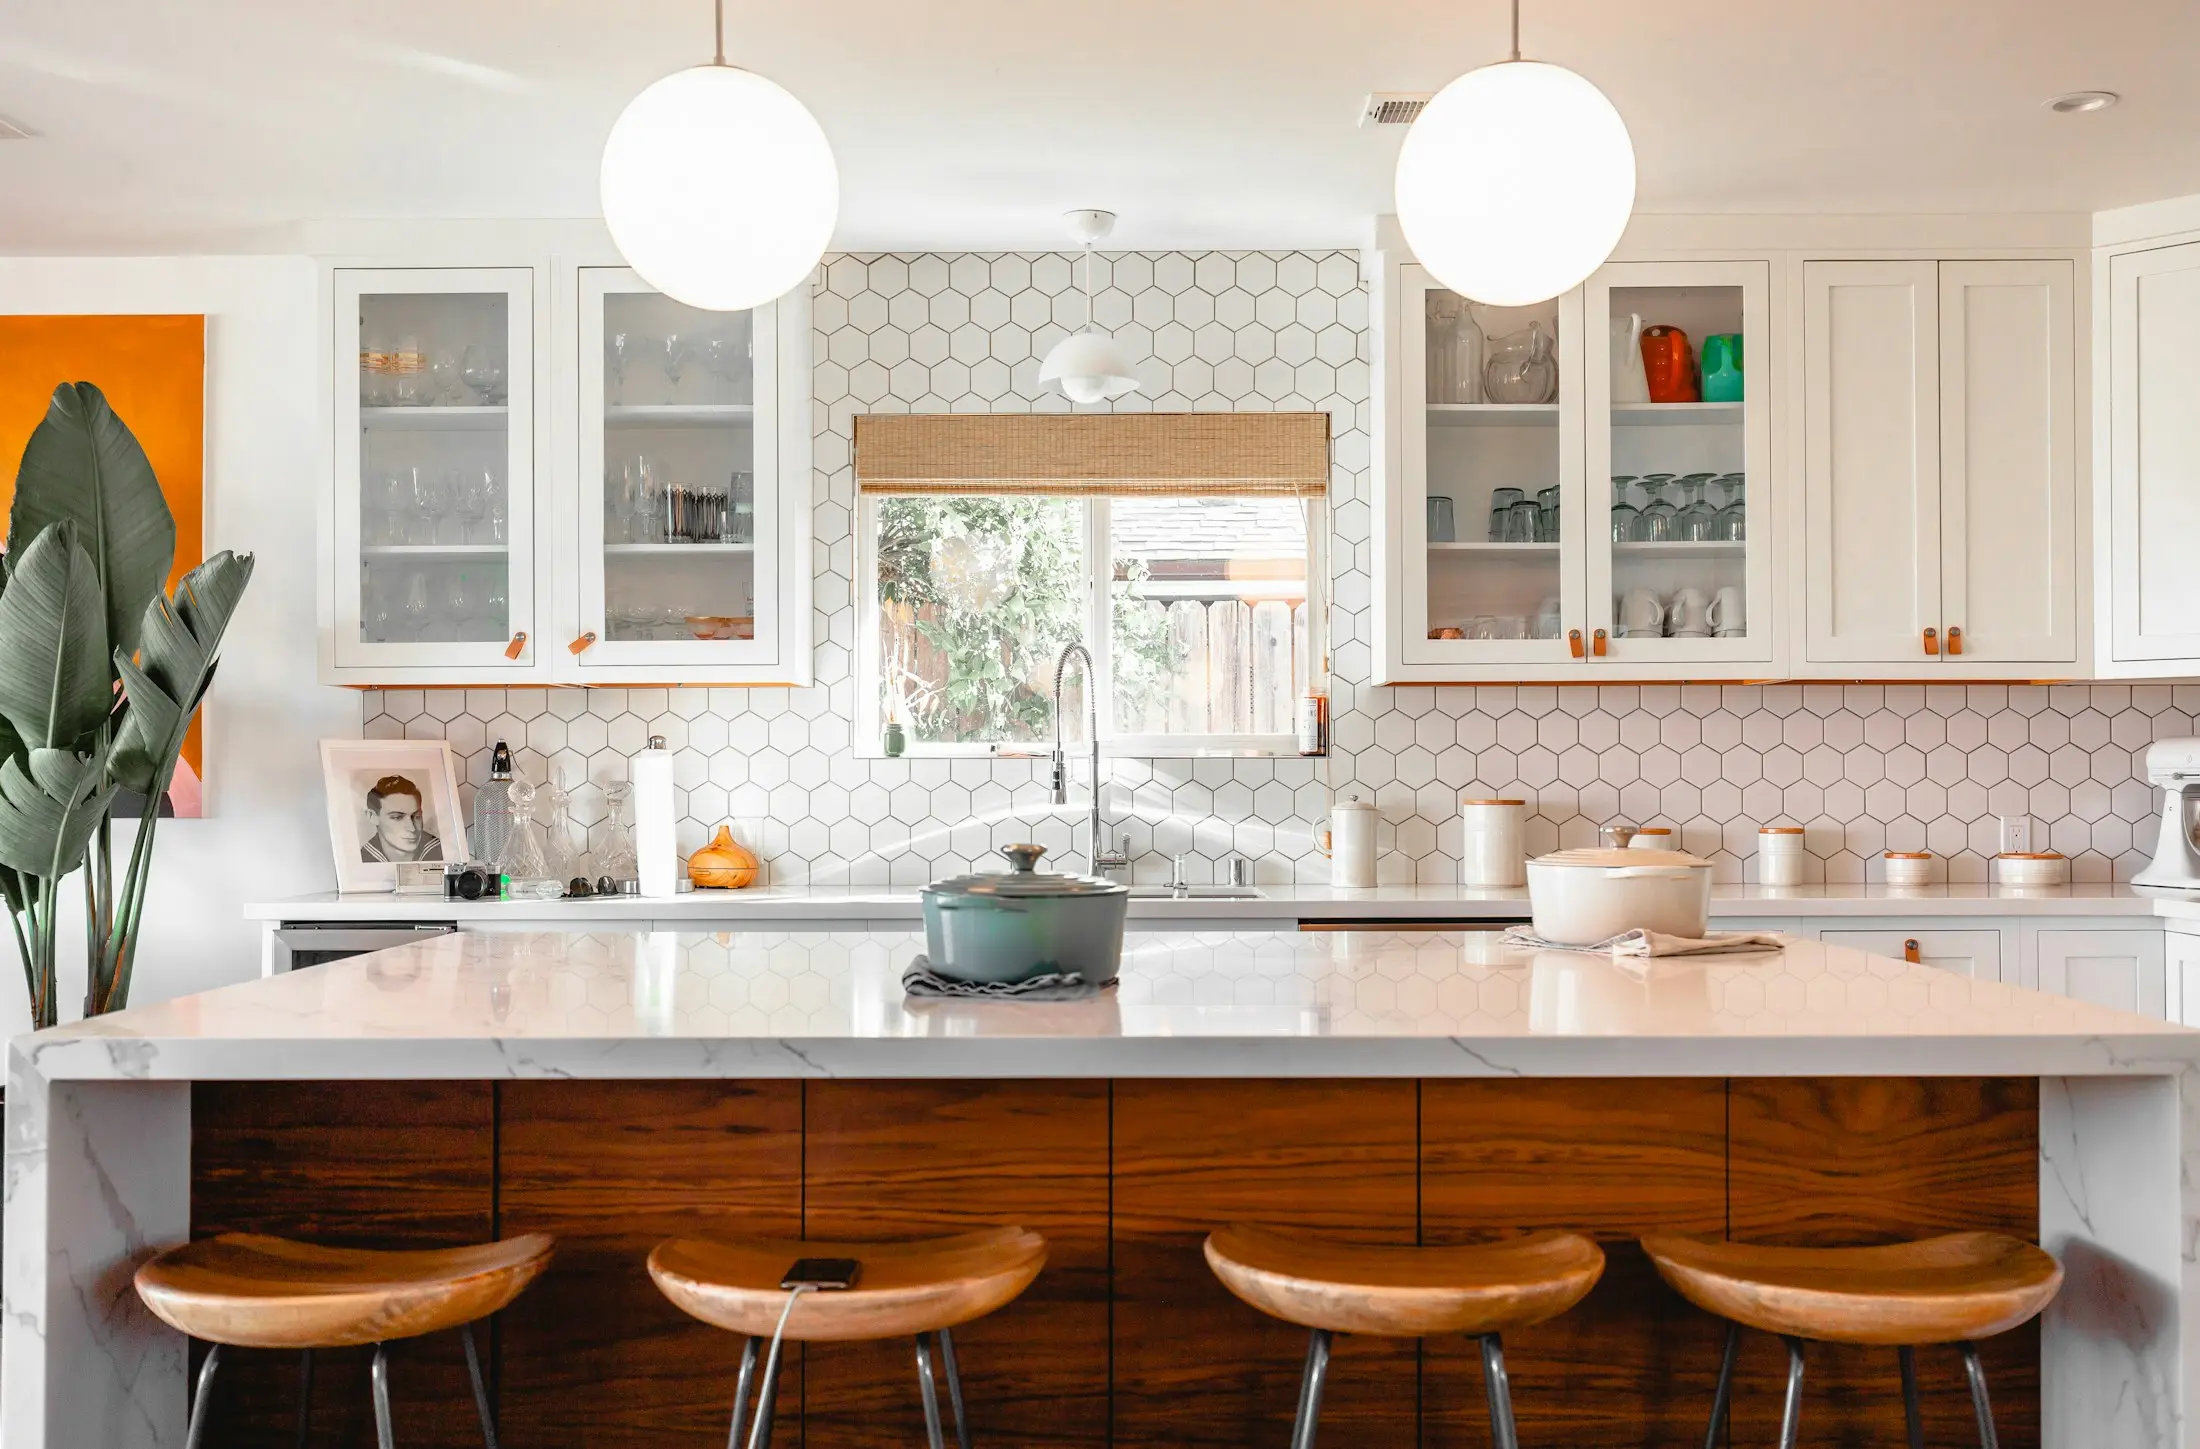
Renovated kitchen with a long island bench and four timber stools
Reno finance, sorted

Renovation loans for the kitchen you keep dreaming about

Morning coffee at a stone benchtop, a bathroom you actually want to linger in. We find the finance that turns the mood board into a finished room.

  • No home equity needed
  • Cover quotes, fixtures and trades
  • Staged payments to suit your builder

Updated September 2026 · Reviewed by our credit team

Step 1 · About 2 minutes

What’s it for?

Pick what the money’s for — we’ll take it from there.

Secure & private · 60+ lenders · No credit check on application

In short

Renovation loans are finance for improving your home — a new kitchen or bathroom, decking, a roof, windows or a granny flat. The usual choice is between an unsecured personal loan, which needs no home equity and can move quickly, and borrowing against their home through a mortgage top-up or refinance. Loan Finder Store compares options across 60+ lenders so you can pick the right route.

  • No equity needed

    A personal renovation loan doesn’t depend on how much of your home you already own.

  • Sized to your quotes

    Borrow for the real scope of works, with room for a contingency buffer.

  • Suits staged payments

    Plan the money around deposits and progress payments so your builder keeps moving.

  • Real people, one team

    Talk to the same team from your first question to settlement, without being bounced between departments.

Renovations people finance

  • Kitchens
  • Bathrooms & ensuites
  • Laundries
  • Decks & pergolas
  • Landscaping
  • Roof restoration
  • Windows & doors
  • Air conditioning
  • Granny flats
  • Flooring
  • Interior & exterior painting
  • Fencing & driveways
  • Built-in storage

How do renovation loans work?

Renovation loans work like any loan with a clear purpose: you borrow a set amount for the project and repay it over an agreed term. The big decision is where the money comes from — a personal loan or your home’s equity.

With a personal renovation loan, the funds usually land in your account at settlement and you pay your trades as work progresses. With a mortgage top-up or refinance, the extra is added to your home loan and repaid over its much longer term.
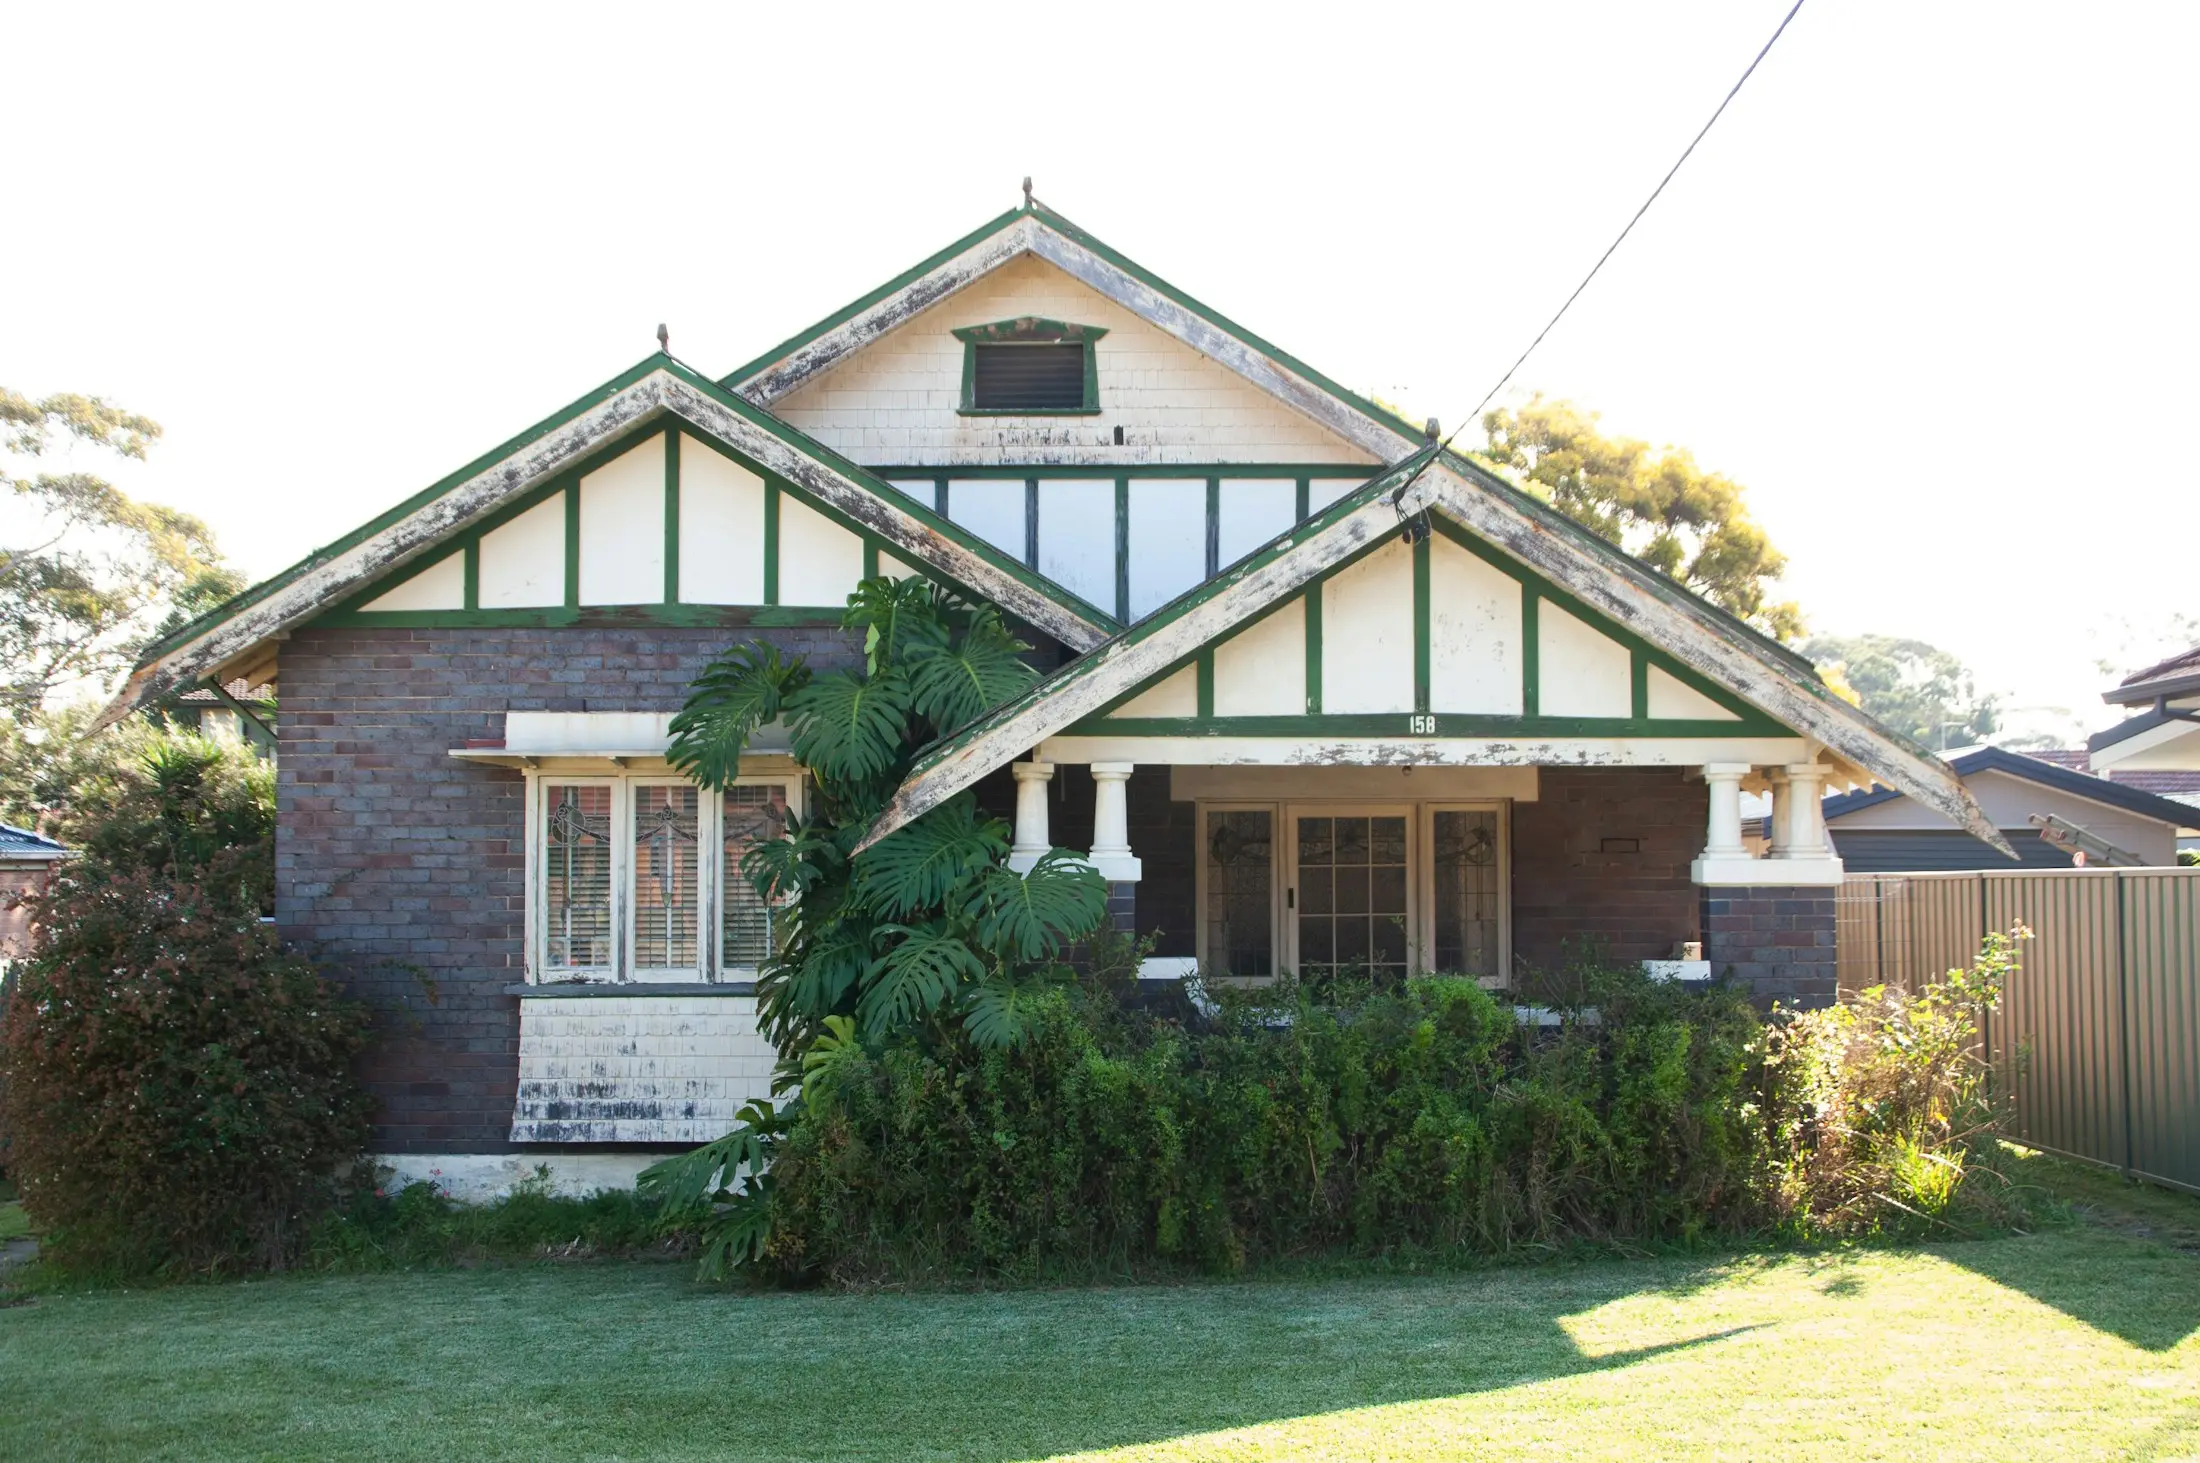
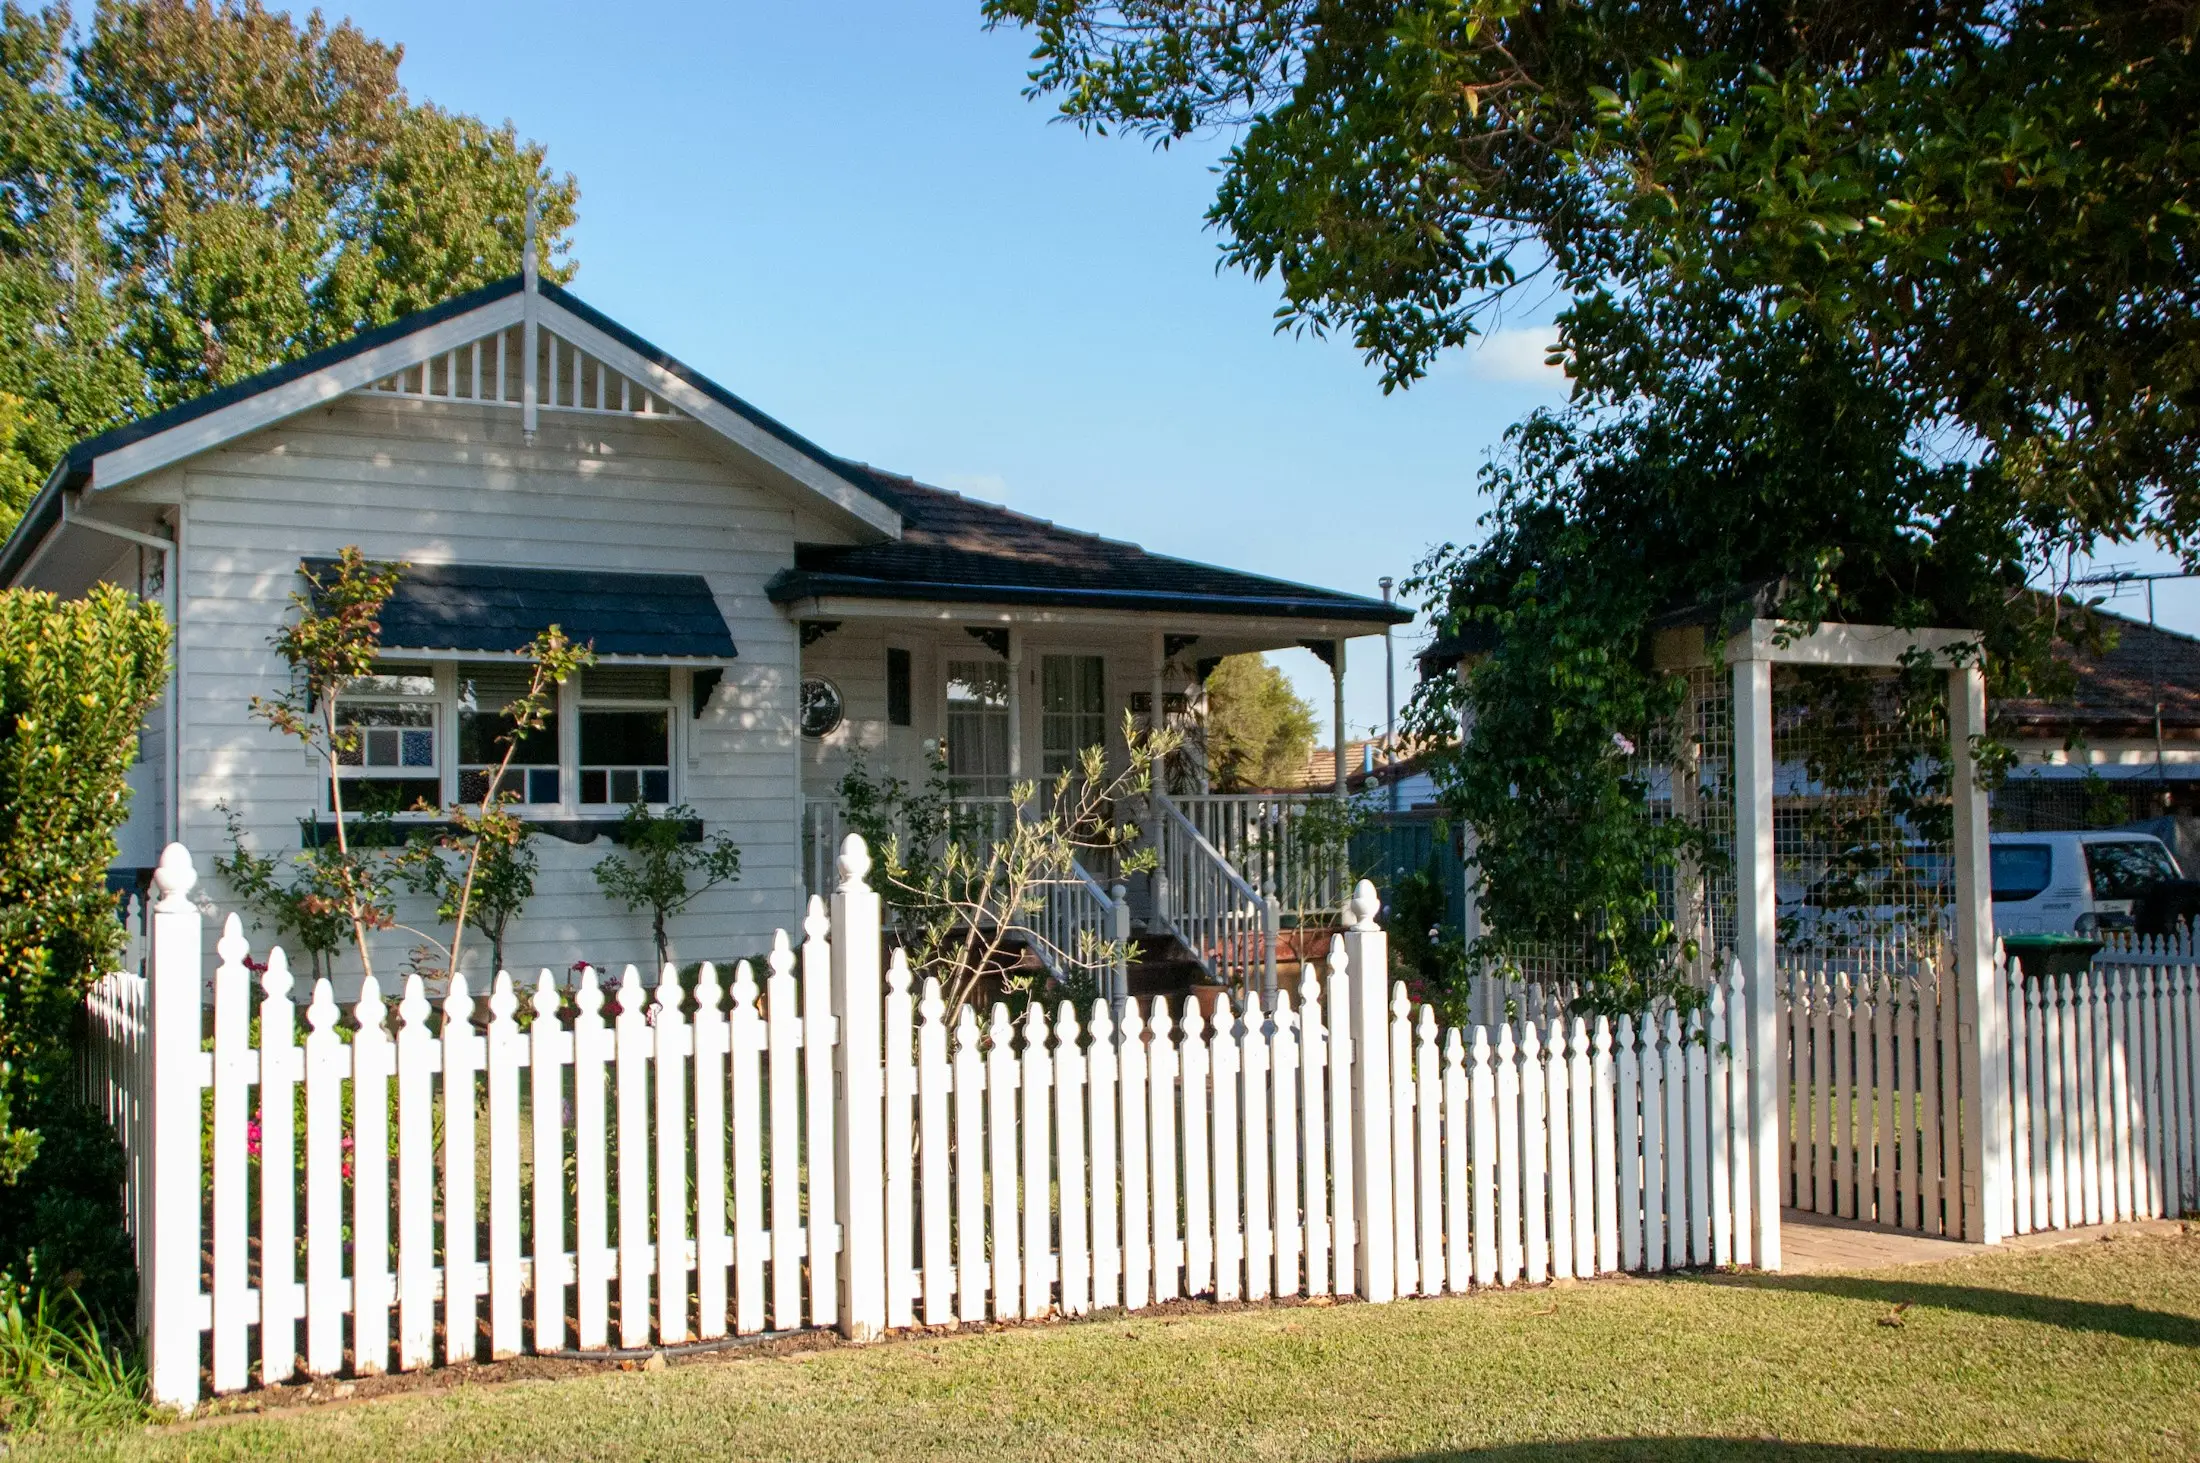
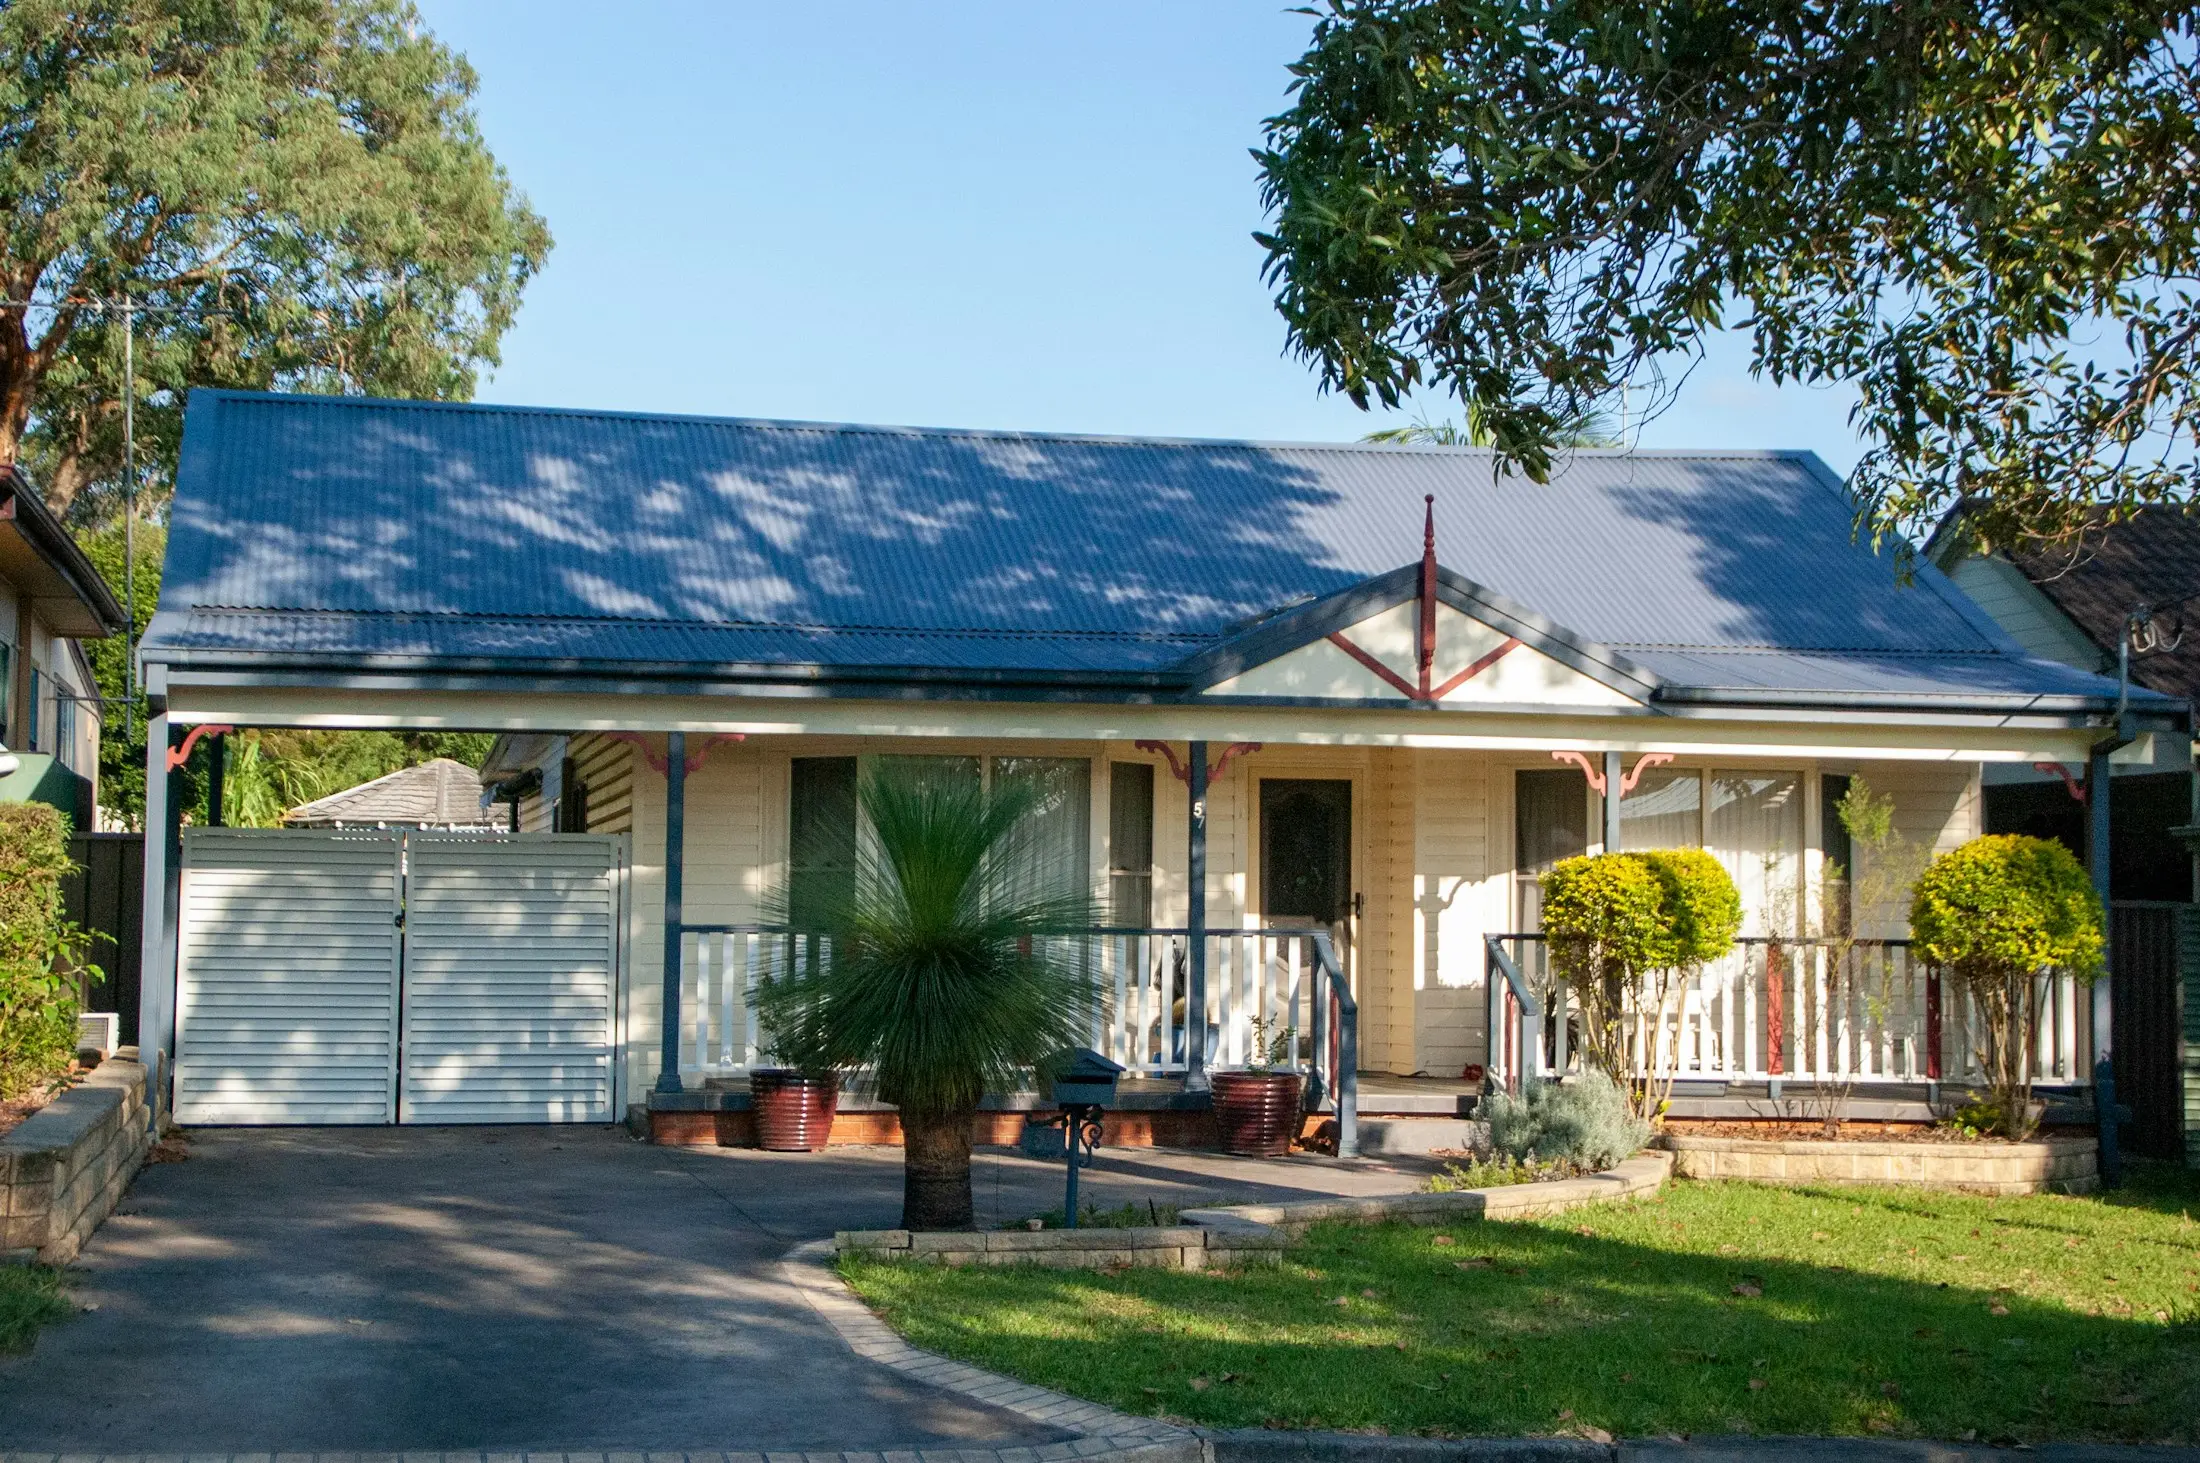
Classic Australian fibro house behind a front fence, ready for a renovation

Personal loan vs using home equity for a renovation

Neither is automatically better. It comes down to the size of the job, how much equity you have and how soon you want the tradies on site.

Two ways to fund a reno
Personal renovation loanMortgage top-up or refinance
Home equity neededNoYes
SecurityUsually unsecuredSecured against your home
Paperwork and timingLighter, often quickerMore involved, may need a valuation
Loan termShorter, with a fixed end dateSpread across the life of your mortgage
Good fit forKitchens, bathrooms, decks and smaller jobsExtensions, granny flats and whole-house projects

Stretching a reno across a long mortgage term can mean smaller repayments but more interest in total. If equity looks like the better route, our specialist team can help with refinancing your home loan.

What renovations can I finance?

Almost any genuine improvement to your home. Here’s how the usual projects shape up:

  • Kitchens: often the biggest spend. Kitchen renovations commonly range from about $15,000 to $50,000+ depending on scope.
  • Bathrooms and laundries: waterproofing, tiling, fixtures and a licensed plumber.
  • Outdoor living: decks, pergolas, paving and landscaping for summer entertaining.
  • The house itself: roof restoration, windows, doors, insulation and air conditioning.
  • Granny flats: a bigger build that usually needs council or certifier approval and often suits equity or a larger loan.
  • Energy upgrades: panels and batteries, with rebates covered on our solar panel finance page.

How much can I borrow for a renovation?

That depends on your income, living costs and existing debts, and on the route you choose. Equity-based borrowing can stretch further because the loan is secured against your property.

Work from your quotes up rather than from a lender’s maximum. Then add the things trades often leave out:

  • Appliances, tapware and light fittings
  • Council or certifier fees
  • Skip bins and rubbish removal
  • Living costs while the kitchen’s out of action
  • A contingency buffer for surprises behind the walls

How do I pay my builder with a renovation loan?

Usually in stages, with you controlling each payment. Most builders ask for a deposit, then progress payments as each stage is finished.

  1. 1

    Lock in a fixed-price quote

    Get the scope, inclusions and payment schedule in writing before you sign.

  2. 2

    Check licences and insurance

    Confirm your builder is licensed, and ask about home warranty insurance where your state requires it.

  3. 3

    Pay the deposit

    Use part of the loan for the deposit and keep the rest aside for progress payments.

  4. 4

    Pay as stages are finished

    Inspect the work before each payment and never pay far ahead of what’s been done.

  5. 5

    Hold back for the final touches

    Where your contract allows, keep the last payment until defects are fixed.

Adding a pool to the plans? Our pool loans page explains how pool builders stage their payments.

What you’ll need

  • Written quotes from your builder or trades
  • Scope of works, plans or a design brief
  • Council approval details, if your project needs them
  • Your driver licence or passport
  • Recent payslips, or tax returns if self-employed
  • Recent bank statements
  • Home loan statement and property details if using equity

Who it usually suits

  • Aged 18 or over and an Australian citizen or permanent resident
  • Own, or be buying, the home you’re renovating
  • Steady income that covers repayments and living costs
  • Existing debts at a manageable level
  • Enough home equity, only if you choose the top-up or refinance route
Repayment calculator

Crunch the numbers

Play with the amount, term and rate to see how repayments change.

Estimate your repayments

$
%
Repayments

Fortnightly repayment

$0

Amount borrowed
$0
Total interest
$0
Total repaid
$0
Find my real rate

This calculator uses the rate you enter and is a guide only — it isn’t a quote. Your actual rate depends on the lender and your circumstances. Fees aren’t included.

How it works

Three steps to yes

We do the searching, comparing and chasing. You get on with planning the fun part.

  1. Tell us what it’s for

    Answer a few quick questions in about 2 minutes. No paperwork, and no impact on your credit score.

  2. We find your match

    We search our panel of 60+ lenders and call you to fine-tune the options that genuinely suit.

  3. Approved and on your way

    Sign digitally, and we look after the rest. Once approved, some lenders can settle within 24 hours.

FAQs

Home renovation loans: your questions answered

Can I get a renovation loan without equity?

Yes. An unsecured personal loan doesn’t rely on home equity at all, which suits people who bought recently or started with a small deposit. Lenders focus on your income, expenses and credit history instead. The trade-off is usually a smaller maximum and a shorter term than borrowing against your home.

Can I use a renovation loan to buy furniture and appliances?

Yes, when they’re part of the project. New ovens, dishwashers, tapware and built-in joinery are common inclusions, and a personal loan can often stretch to loose furniture too. List everything in your enquiry so the loan amount matches the whole job, not just the builder’s quote.

Is a home improvement loan tax deductible?

Generally not for the home you live in, because the renovation is a private expense. For an investment property, interest on money borrowed for the property may be deductible, and the work itself is treated differently depending on whether it’s a repair or an improvement. Check with your accountant or the ATO before relying on it.

Can I get a renovation loan with bad credit?

It’s possible. Some lenders we work with focus on where you are now rather than a default from years ago, so steady income and a clean recent record go a long way. Approval isn’t guaranteed and the loan needs to be affordable, so we’ll be upfront about what’s realistic before any application goes in.

Can I finance a granny flat?

Yes. Granny flats are bigger projects, so many owners use home equity or a larger personal loan, sometimes both. You’ll typically need council or certifier approval, and the build runs on staged payments. Share your quotes and approval status with us and we’ll work out which structure suits.

What if my renovation goes over budget?

Plan for it before it happens. Building a contingency buffer into the original loan is usually easier than applying for more finance mid-project. If you do fall short, options may include a second personal loan or a home loan top-up, depending on your situation and the lender.

Are renovation loans hard to get?

Not usually, if the numbers stack up. Lenders want to see steady income, manageable debts and a clear purpose backed by quotes. Having your documents ready and a realistic budget makes things smoother — and enquiring with us won’t affect your credit score while you explore your options.

General information only — it doesn’t take into account your personal circumstances. Credit is subject to lender approval, terms and fees.

Classic Australian fibro house behind a front fence, ready for a renovation

Your plans, funded. Let’s find the way.

One short form, 60+ lenders searched, and a real person in your corner. It takes about 2 minutes.

Get my options Enquiring won’t affect your credit score